ByJohn A
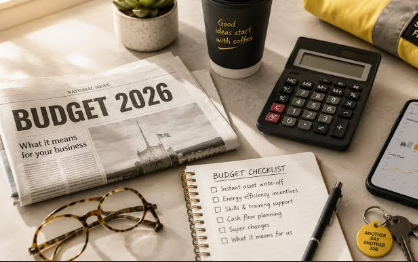
Small Business Budgeting Made Simple for 2026
Effective financial management is the cornerstone of any sustainable enterprise. For small business owners and digital entrepreneurs navigating the complexities of the commercial ecosystem, a well-structured budget acts as an early warning system rather than a restrictive financial cage. In 2026, relying on static spreadsheets or guesswork is no longer sufficient; macroeconomic shifts, fluctuating supply chains, and evolving consumer habits require dynamic, data-driven financial planning. Whether you are managing lean operations or scaling multi-channel digital assets, mastering your numbers guarantees operational control and long-term viability.
However, balancing operational expenses, emergency reserves, and growth initiatives requires more than internal cost-cutting; it requires strategic visibility and customer acquisition. To stimulate continuous revenue growth and attract high-intent buyers, organizations must actively advertise a business through optimized digital channels while maintaining strict control over overhead costs. This comprehensive guide outlines the exact framework required to simplify small business budgeting, protect cash flow, and maximize profitability in 2026.
1. Establishing a Realistic Revenue and Expense Baseline
Every effective budget begins with an objective assessment of historical financial data and current market conditions. Skipping this baseline phase leads to inflated growth projections and sudden cash shortages.
+———————————————————————————–+
| Historical Baseline vs. Realistic Projections |
+———————————————————————————–+
| Blind Projections| Guessing top-line revenue without checking 12-month trends |
| Data Baseline | Analyzing past P&L statements, seasonal dips, and fixed costs |
+———————————————————————————–+
Review your profit and loss (P&L) statements from the past 12 to 24 months to identify cyclical purchasing patterns, seasonal revenue dips, and recurring operational overhead. Separate your expenses rigidly into two distinct categories: fixed costs (such as commercial rent, software subscriptions, insurance, and payroll) and variable costs (such as raw materials, production shipping, and contractor fees). When estimating future income, adopt a conservative forecasting approach. Under-promising on expected cash inflows protects your operating margins if market conditions temporarily soften.
2. Differentiating Operating Budgets from Cash Flow Forecasting
A common point of failure for growing small businesses is confusing profitability with liquidity. A company can show strong net income on paper while simultaneously going bankrupt due to poor cash timing.
+———————————————————————————–+
| Operating Budget vs. Cash Flow Management |
+———————————————————————————–+
| Operating Budget | Tracks overall profitability, annual revenues, and fixed overhead|
| Cash Flow Model | Maps the exact weekly timing of cash inflows and outflows |
+———————————————————————————–+
While an operating budget measures long-term business model viability, a cash flow statement tracks the actual movement of money in and out of your bank accounts week by week. Long client payment terms or heavy upfront inventory purchases can trap capital, making it difficult to pay immediate liabilities. Maintaining a dedicated cash reserve that covers three to six months of baseline operating expenses insulates your enterprise against unexpected payment delays.
3. Allocating Dedicated Funds to Marketing and Growth Initiatives
Many small business owners treat marketing expenditures as an arbitrary expense line that gets slashed at the first sign of a tight month. In reality, strategic customer acquisition is an investment that directly fuels future revenue.
+———————————————————————————–+
| Strategic Marketing Budget Allocation Framework |
+———————————————————————————–+
| Organic Channels | Content SEO, email automation, and organic social engagement |
| Paid Acquisition | Targeted PPC campaigns and social ads to **advertise a business** |
+———————————————————————————–+
Allocate a predictable percentage of projected gross revenue—typically between 7% and 12% depending on your industry—toward consistent marketing activities. Whether you are running search engine ads, nurturing email subscribers, or deploying social media campaigns to advertise a business effectively, treating marketing as a fixed growth engine prevents feast-or-famine revenue cycles. Always track your customer acquisition cost (CAC) against customer lifetime value (LTV) to ensure every marketing dollar spent generates a positive, measurable return.
4. Integrating Contingency Planning and Emergency Buffers
Economic volatility, unexpected tax adjustments, and supply chain disruptions can instantly derail even the most meticulously planned annual budget. Building financial resilience is non-negotiable for small business survival.
+———————————————————————————–+
| Contingency Planning & Risk Mitigation Matrix |
+———————————————————————————–+
| Scenario Stress-Testing| Simulating a 15% revenue drop to test expense flexibility|
| Emergency Reserves | Setting aside 5-10% of monthly net income for unforeseen shocks|
| Tax Projections | Allocating quarterly tax liabilities automatically before spending|
+———————————————————————————–+
Establish a dedicated contingency fund separate from your primary operating capital. Treating emergency fund contributions as a mandatory fixed expense protects your business from taking on high-interest debt when unexpected equipment failures or market shifts occur. Furthermore, when businesses successfully scale operations and need to advertise a business expansion into new regional markets, having a pre-secured financial safety net ensures growth initiatives never compromise daily cash liquidity.
See also: The Impact of Digital Independence on Businesses
5. Automating Expense Tracking and Leveraging Modern Financial Software
Manual data entry and paper receipt filing introduce human error, waste valuable administrative hours, and obscure real-time financial visibility. Modern budgeting relies entirely on integrated cloud software.
+———————————————————————————–+
| Manual Spreadsheets vs. Automated Cloud Accounting |
+———————————————————————————–+
| Manual Tracking | Error-prone formulas, delayed expense reporting, blind spots |
| Cloud Automation | Real-time bank feeds, automated categorization, instant P&L views|
+———————————————————————————–+
Adopt user-friendly accounting platforms—such as QuickBooks, Xero, or specialized fintech dashboard tools—that sync directly with your corporate bank accounts and credit cards. Automated transaction feeds categorize expenses instantly, allowing you to run monthly budget-versus-actual variance reports. Maintaining clean, up-to-date digital books ensures you always know your exact financial position before deciding to advertise a business initiative or hire new staff.
6. Conducting Regular Monthly Reviews and Financial Health Audits
A budget is not a static document created once in January and hidden away in a filing cabinet until the end of the year. It is a living roadmap that requires continuous monitoring and agile adjustment.
+———————————————————————————–+
| Monthly Budget Review & Adjustment Workflow |
+———————————————————————————–+
| Variance Analysis | Compare budgeted line items against actual monthly spending |
| Overhead Audits | Review recurring software and vendor costs every six months |
| Agile Reallocation | Shift funds dynamically from underperforming to high-yield areas |
+———————————————————————————–+
Schedule a dedicated “finance hour” at the conclusion of each month to evaluate your P&L statement, check cash flow velocity, and analyze spending variances. If certain variable expenses creep upward or projected sales fall short, identify the root cause immediately and adjust your operational spending. Regular oversight ensures small problems are corrected before they evolve into major financial crises.
7. Consulting Professional Advisors for Tax and Growth Optimization
As small businesses mature, tax regulations, compliance requirements, and corporate structuring decisions become increasingly complex. Trying to handle advanced accounting entirely in-house can lead to missed deductions and legal risks.
+———————————————————————————–+
| In-House Bookkeeping vs. Professional CPA Advisory |
+———————————————————————————–+
| Basic Bookkeeping | Managing daily invoicing, receipts, and basic bank reconciliations|
| Fractional CPA | Strategic tax planning, custom financial forecasting, growth advice|
+———————————————————————————–+
Partnering with a qualified Certified Public Accountant (CPA) or outsourced fractional financial controller provides invaluable strategic insight. Professional advisors ensure your tax liabilities are estimated correctly, identify overlooked deductions, and help you allocate capital efficiently when you are ready to advertise a business expansion or seek external financing. Proactive tax planning eliminates year-end surprises and preserves bottom-line profitability.
Frequently Asked Questions (FAQs)
What is the 50/30/20 rule for small business budgeting?
The 50/30/20 framework suggests allocating 50% of revenue to essential fixed operating expenses (rent, payroll, utilities), 30% to variable discretionary costs (marketing, software, travel), and 20% to profit, debt reduction, and emergency reserves. While adjustments are necessary depending on your specific industry, it provides a helpful starting baseline.
How often should I review and update my small business budget?
You should conduct a formal budget review on a monthly basis, comparing projected revenue and expenses against actual performance metrics. Additionally, performing a comprehensive strategic review and forecast update every quarter ensures your business remains agile against shifting market conditions.
Why is budgeting essential when you advertise a business?
Creating a clear budget prevents marketing funds from being spent haphazardly. By establishing strict customer acquisition cost limits within your financial plan, you ensure that every dollar used to advertise a business campaign generates a verifiable, profitable return on investment without jeopardizing your baseline operating cash flow.
Conclusion
Simplifying small business budgeting in 2026 requires shifting away from rigid spreadsheets toward dynamic, cash-flow-conscious financial management. By establishing a reliable historical baseline, separating operating budgets from liquidity tracking, automating expense monitoring, and maintaining emergency reserves, small business owners can eliminate financial anxiety. Furthermore, coupling disciplined cost control with targeted marketing investments—ensuring you strategically advertise a business to high-intent audiences—drives predictable, sustainable growth. Implementing these foundational budgeting practices today positions your enterprise for long-term operational stability and uncompromised commercial profitability.